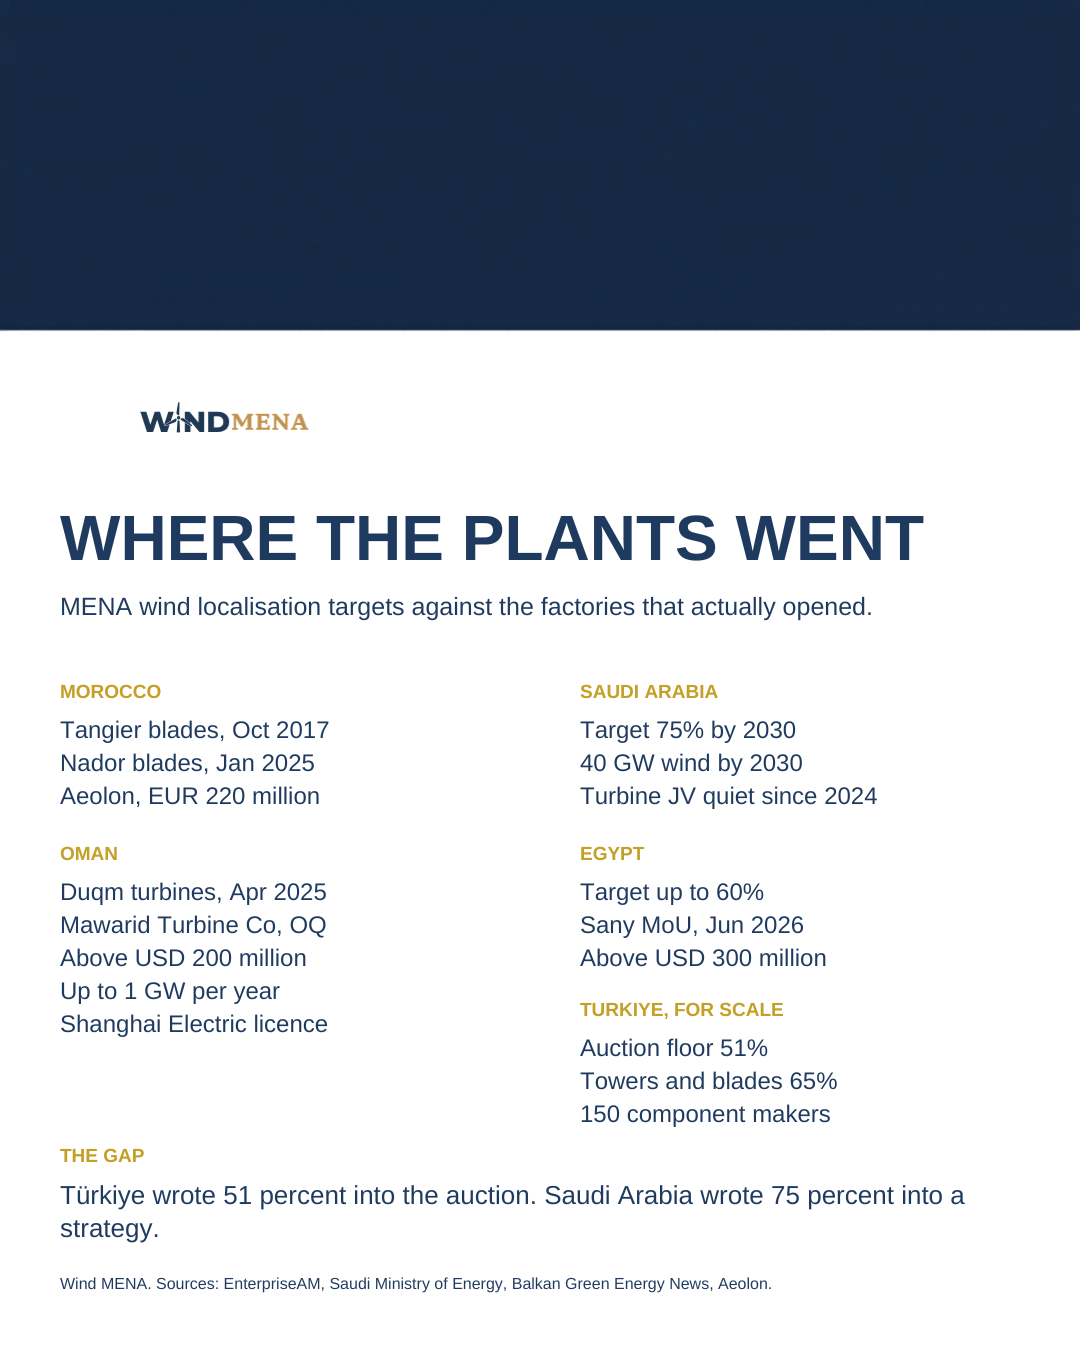
Saudi Arabia wants 75 percent of its renewable equipment made at home by 2030. It is the most aggressive localisation mandate in the region. The turbine joint venture PIF’s localisation arm signed with Envision Energy in 2024 has been quiet since.
Türkiye chose a lower number and put it somewhere harder. To win state support in a YEKA auction, every component has to clear 51 percent domestic content, and towers and blades have to clear 65. Miss it and you do not win. Türkiye now counts roughly 150 wind component manufacturers.
The MENA plants that actually exist followed the same logic. Morocco has been making blades in Tangier since October 2017 and added Aeolon at Nador, a EUR 220 million plant and the company’s first outside China. Oman broke ground at Duqm in April 2025, above USD 200 million, up to 1 GW a year on Shanghai Electric technology. Egypt has a Sany memorandum from June and a target of up to 60 percent.
Morocco and Oman answered the demand question before pouring concrete. Morocco pointed its plants at export markets. Oman had OQ take equity in the wind projects that will buy the turbines.
The number a country publishes tells you its ambition. The number it writes into a bid tells you where the factory goes.