MENA wind’s next real price test arrives with the first operating year.
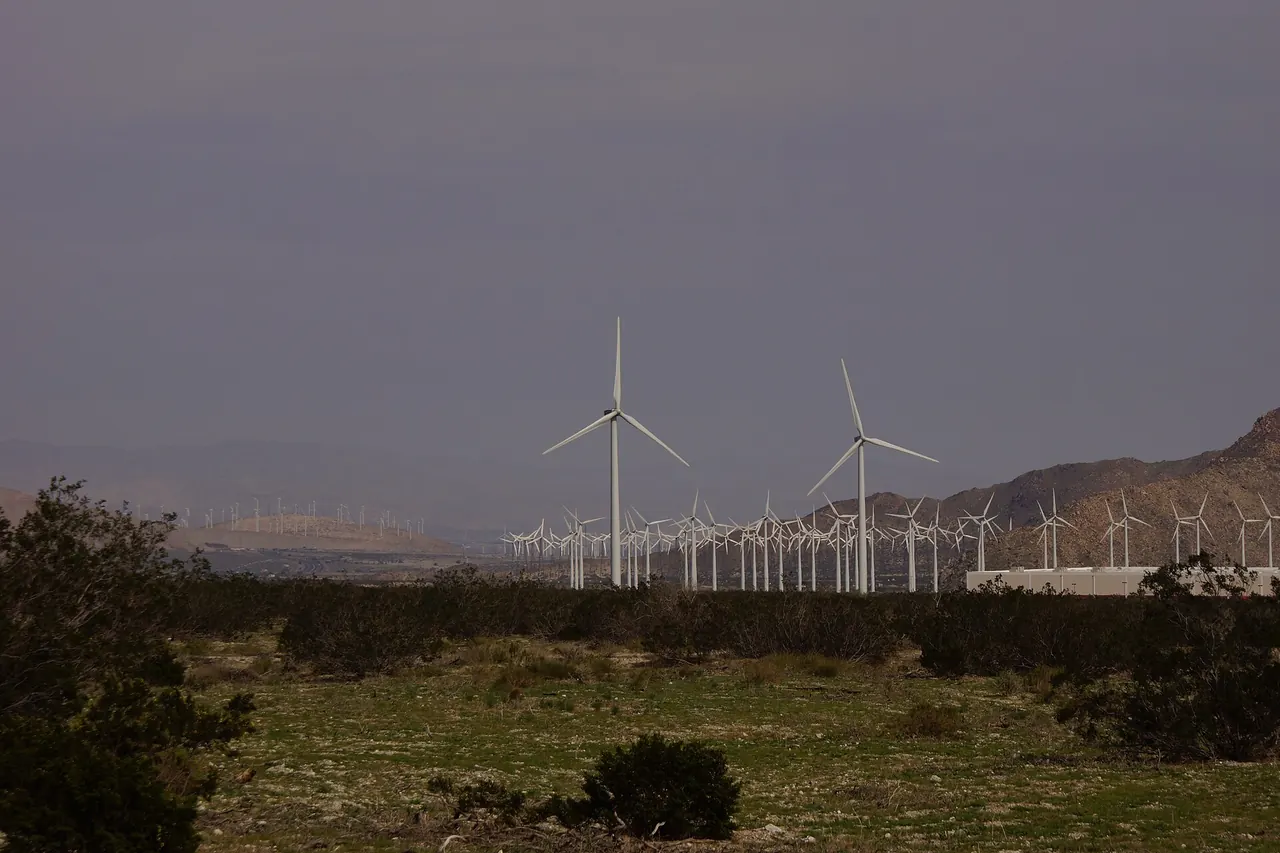
Saudi Al-Ghat’s 600 MW cleared at 1.566 cents per kWh under a 25-year SPPC PPA and is now fully grid-connected. Wa’ad Al Shamal’s 500 MW reached full grid synchronization on June 25, with both projects pending the 168-hour reliability run before commercial operation. The same Marubeni and Ajlan partnership is building Yanbu 700 MW behind them. NREP Round 7 wind bidding falls into that same window.
Those prices were set before either site had a year of operating data at hub height. From Q3 2026, that data starts arriving. Availability rates, curtailment behaviour, dust and thermal loss profiles all land at project meters over the next four quarters. I expect lenders and procurement offices to read those numbers before they underwrite the next tender.
That is the test. If Round 7 clears near current levels once the first operating year is public, I would read the sub-2-cent floor as a real market clearing price. If Round 7 clears wider, operating reality has repriced the market.
Which way does it go?